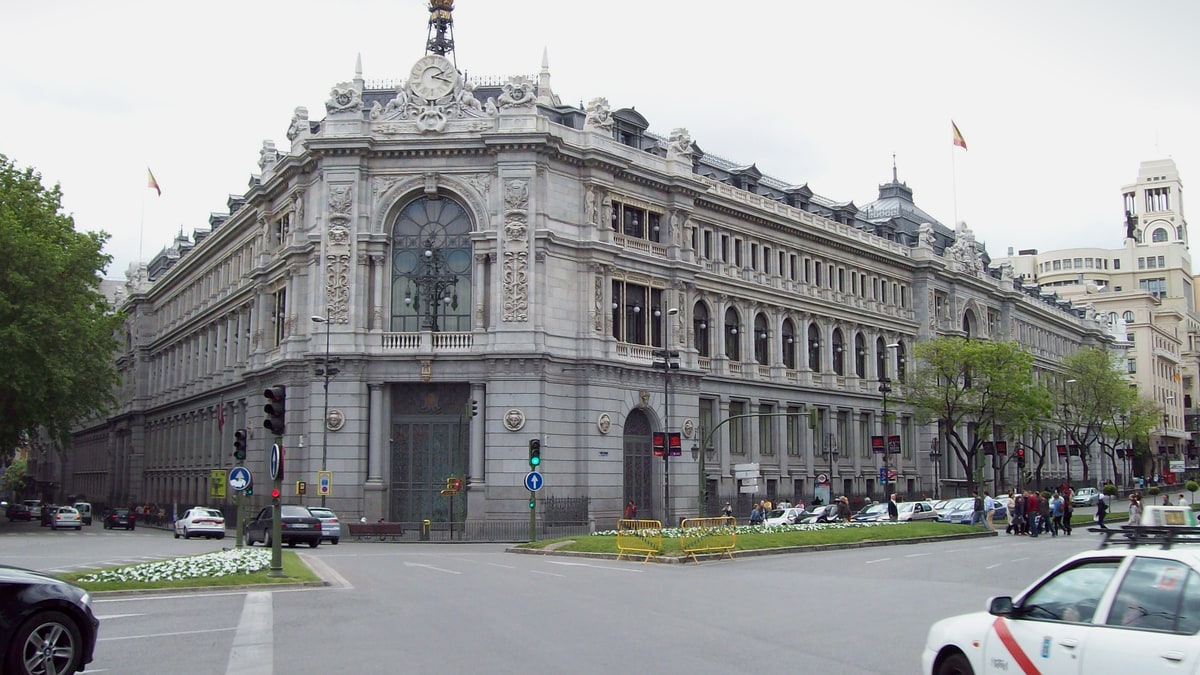
The Bank of Spain has fined Sabadell €16.5 million for tied selling in mortgages. Those who signed a loan conditioned on insurance can claim the cost difference.
According to que.es, the Bank of Spain has imposed a fine of €16.5 million on Sabadell for tied selling practices, in a resolution published in the BOE on 20 November. The sanction was imposed on 26 May 2025.
The supervisor classifies the infringement as very serious for two reasons: the bank imposed products linked to the loan without offering alternatives and did not act impartially in defending the client's interests. The public file does not detail how many transactions were affected or what products formed each combination, although it does indicate the number of transactions and the recurrence of the conduct as relevant factors.
The banking sanction regime allows fines of up to 10% of the net annual turnover of the previous year for very serious infringements. It also contemplates triple or quintuple the profit obtained, when quantifiable, and up to €10 million when the percentage falls below that amount.
The resolution is firm in the administrative route, but Sabadell has appealed to the courts, so it is not yet firm in the judicial route.
The Law 5/2019, on real estate credit, requires separating the loan from ancillary products. In tied selling, the bank does not offer the loan separately, except for legal exceptions. In combined selling, the mortgage can be contracted alone, although the bank must inform in writing of the differences and costs of each option.
In insurance, the bank can require a policy that guarantees the compliance of the loan or a damage insurance on the property, but must accept alternatives from other insurers with equivalent conditions, both when contracting and at each renewal. It also cannot charge for analysing those alternatives nor worsen the loan conditions for accepting an external policy.
To claim, it is advisable to gather the binding offer, the deed, the insurance conditions, and any communication in which the mortgage was conditioned to a specific product. With that documentation, a written claim is submitted to the customer service of the entity, keeping the receipt with the date. If the response does not arrive on time or is unsatisfactory, one can go to the complaints service of the Bank of Spain, the Municipal Arbitration Board for Consumption, or organisations like OCU or Facua.
The fine does not return money to customers: it is deposited in public coffers. To recover the overcost of the imposed insurance, one must claim case by case, with the policy, the premiums paid, and the conditions of the offer.
You may also like