The European Central Bank sets interest rates in the eurozone. Its decisions are felt in the payments of variable mortgages and in the returns on deposits.
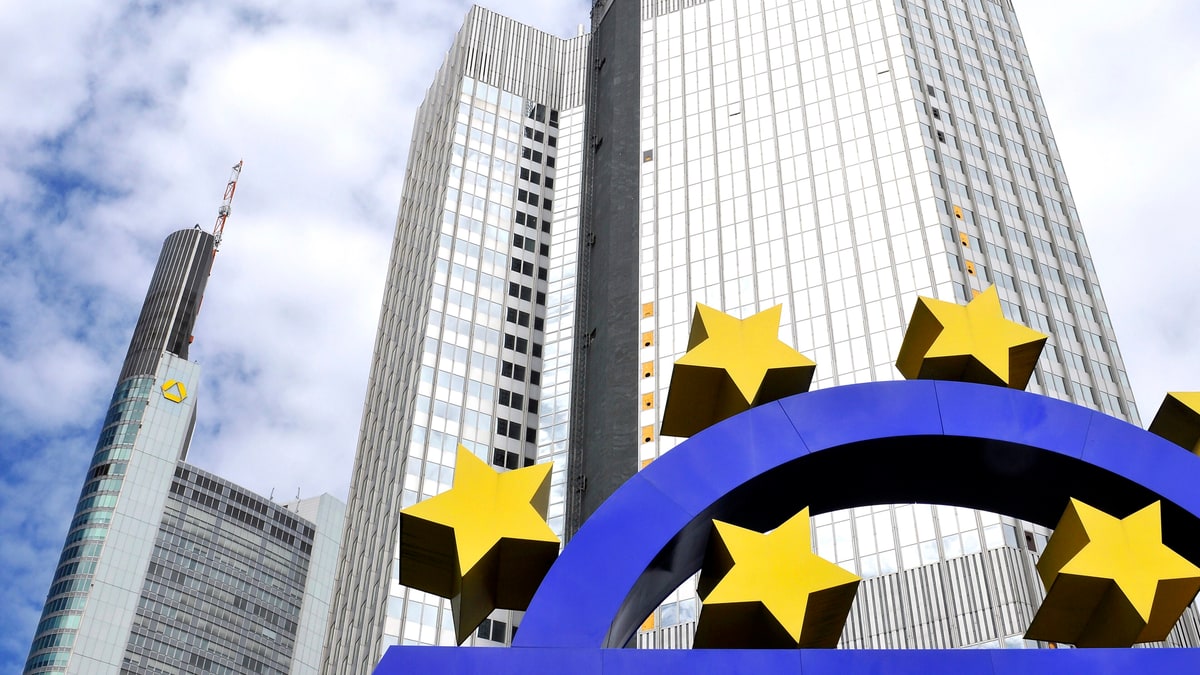
As reported by economiadigital.es, the European Central Bank, based in Frankfurt, is responsible for determining the official interest rates of countries using the euro. Its goal is to keep inflation under control, and to achieve this, it raises or lowers the cost of money.
The interest rate is the price paid for a loan and is expressed as a percentage. When the central bank raises it, borrowing money becomes more expensive. When it lowers it, credit becomes cheaper, facilitating consumption and business investment.
In variable-rate mortgages, the payment increases when the cost of money rises, as it depends on the evolution of the rates. In fixed-rate mortgages, the payment remains stable throughout the life of the loan, regardless of any increases or decreases.
The effects are not immediate. They can take weeks or even months to translate into the economy. In mortgages, it depends on when the loan review is scheduled, which usually occurs every six months or annually. If the review falls in March, for example, decisions made afterwards will not be reflected until that date.
The rates also affect other loans, such as car loans, renovations, or a business project financed with credit. In savings, with low rates, deposits offer limited returns, pushing many investors towards higher-risk products. With high rates, banks usually have more room to reward term deposits and interest-bearing accounts.
Although the European Central Bank sets the general trend, each bank defines its product catalog. Therefore, mortgages, loans, and savings accounts can vary considerably from one institution to another.
The experts cited in the information recommend not making impulsive decisions due to short-term rate movements, periodically reviewing mortgages and loans, and maintaining a savings cushion to face unforeseen events.
You may also like